SK hynix vs. Hyundai Motor: Polar Opposite Q1 Earnings Analysis Report
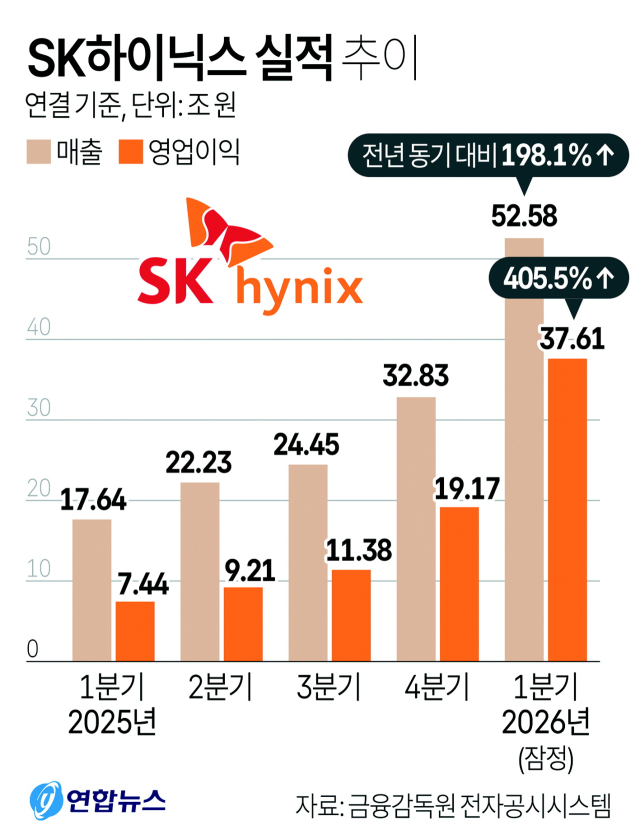
Market summary and analysis
The first-quarter results of two companies representing the Korean stock market have diverged sharply
SK hynix posted record-breaking results on the AI semiconductor boom, but Hyundai Motor's operating profit fell sharply due to U.S. tariffs and raw material cost burdens, making differentiation by industry increasingly clear
Key earnings trends by company
Hynix's AI dominance: It achieved a phenomenal record with Q1 operating profit of 37,610.3 billion won and an operating margin of 72%
As demand for high-value-added products such as high bandwidth memory (HBM) exploded, its financial structure improved dramatically, and it has even announced plans to mass-produce 7th-generation HBM next year, strongly leading the supercycle
Hyundai Motor hit by multiple headwinds: Revenue reached a record high of 45,938.9 billion won, but with U.S. auto tariffs, rising raw material prices and instability in the Middle East combining, operating profit fell 30.8% year on year to just 2,514.7 billion won
Implications from an investor's perspective
As AI infrastructure investment expands, the structural growth of the memory semiconductor value chain is expected to accelerate further, so a strategy of increasing weightings in related materials, parts and equipment companies is effective
On the other hand, in the auto sector, despite solid revenue growth, geopolitical risks such as tariffs and cost control have emerged as key variables determining profitability, so conservative risk management is needed