SK hynix: Going 10 Times Further!...
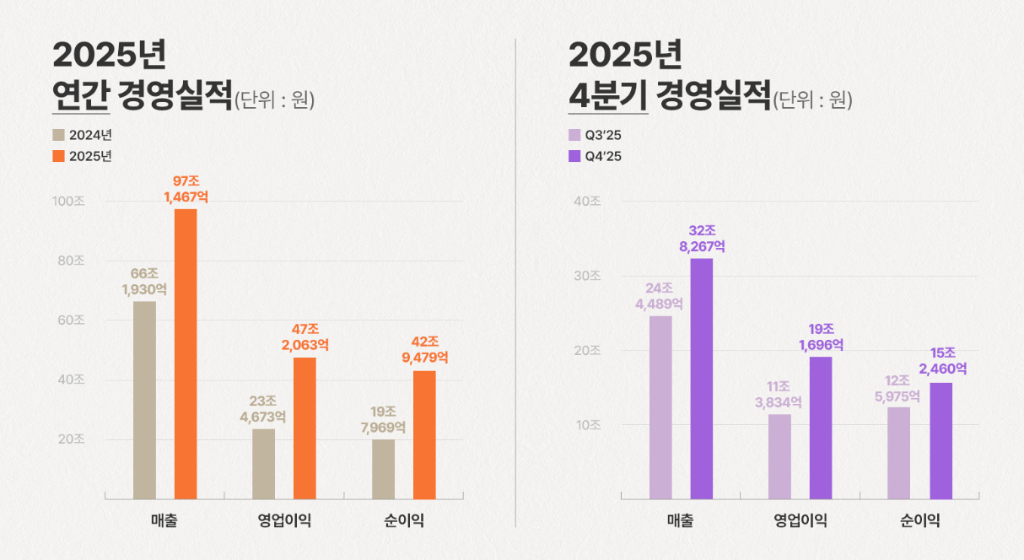
2025 business results: 'quality of earnings' proven by overwhelming numbers
In 2025, SK hynix went beyond a mere earnings improvement to set a new milestone in the history of memory semiconductors.
- Annual results: Revenue of 97.1 trillion won, operating profit of 47.2 trillion won (operating margin of 49%)
- Q4 profitability (OPM 58%): An operating margin of 58% in manufacturing is a figure usually seen only at monopolistic platform companies. It means SK hynix holds complete pricing power in the HBM market.
Core technological competitiveness: Why SK hynix? (MR-MUF)
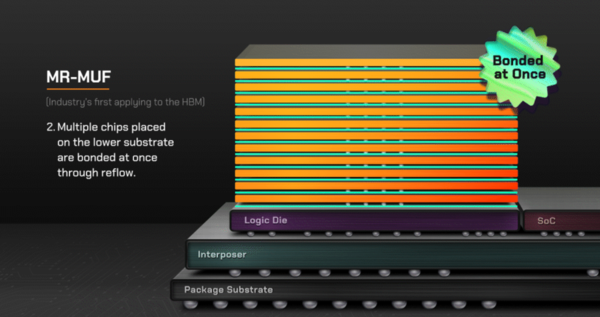
While competitors struggled with HBM yield problems, the decisive secret behind SK hynix's runaway lead lies in its proprietary packaging technology, 'MR-MUF'.
What is MR-MUF (Mass Reflow Molded Underfill)?
Concept: A technology that, when stacking chips, fills the spaces between them with a liquid protective material and hardens it all at once.
Technological edge: The film method (TC-NCF) used by competitors requires pressing and stacking chips one at a time, which takes a long time and makes heat dissipation difficult. MR-MUF, by contrast, has a fast process speed and overwhelmingly superior heat dissipation efficiency.
Why it succeeded: AI semiconductors are a battle against 'heat.' Thanks to MR-MUF technology, which cools heat well, SK hynix was able to secure the earliest and most stable yields in the HBM3 and HBM3E markets, and this became the technological moat behind its exclusive supply to NVIDIA.
Next-generation roadmap (HBM4): For HBM4, to be mass-produced next year, it will apply an improved 'Advanced MR-MUF' to maintain its technology gap, while strengthening its market dominance with a custom HBM strategy using customer-tailored logic dies.
Leadership and history: how a 13 trillion won company became 536 trillion won
Chairman Chey Tae-won emphasized that the current success is not a coincidence but the result of 'meticulous preparation.'
- A masterstroke, the 2011 acquisition: At the time of the acquisition, Chairman Chey pushed it through despite fierce opposition inside and outside the group. In particular, he insisted on the 'new share subscription' method so that the acquisition funds flowed into Hynix itself rather than to the creditors, priming R&D investment. This became the fundamental strength that allowed it to endure downturns.
- 100-to-1 interviews: Right after the acquisition, he held in-depth one-on-one interviews with 100 executives to understand Hynix's distinctive 'wild spirit,' and combined it with SK's systematic management.
- The NVIDIA–TSMC–SK alliance: By anticipating the arrival of the AI era and continuing to invest in HBM preemptively, it became the only partner able to respond immediately at the decisive moment when NVIDIA needed HBM. Chairman Chey looked back on this as "a victory of timing and the result of being prepared."
Future vision: toward the era of 1,000 trillion won in market capitalization
Rather than resting on its current achievements, SK hynix has set out bigger goals as the 'Global No.1 AI Memory Provider.'
- The dream of 10x growth: Chairman Chey said, "SK hynix must become 10 times bigger than it is now," expressing his ambition to open the era of 1,000 trillion won and 2,000 trillion won in market capitalization.
- Entering the U.S. AI ecosystem: Establishing a 10 billion dollar U.S. subsidiary and building production bases is not mere expansion. It signifies a transformation into a 'service-oriented manufacturer' that communicates directly where Big Tech (its customers) is and supplies customized products.
Shareholder returns: sharing the fruits of growth
Shareholder-friendly policies befitting record earnings are further cementing the market's trust in the company.
- 12.2 trillion won treasury share cancellation: Cancelling 2.1% of all shares immediately raises per-share value.
- Expanded dividends: A dividend of 3,000 won per share delivers real profit sharing.
💡
"Structural growth built on a technological moat (MR-MUF)"
SK hynix's latest earnings announcement is not simply the peak of a semiconductor cycle. It confirmed that, based on its unique process technology MR-MUF, the company has built barriers to entry that competitors cannot catch up with in a short time.
Just as Chairman Chey Tae-won's management philosophy of "investing boldly in times of crisis" bore fruit in HBM, its current U.S. investment and strategy to lead in HBM4 are expected to become a powerful engine on the way to becoming a 1,000 trillion won market cap company.