This Year in Semiconductors, Watch AI Substrates
The substrate industry is back in the spotlight
- Past
Substrate = custom-order component
→ Customers set the unit price; suppliers had no bargaining power
- Present
Emergence of AI semiconductors + larger area, higher layer count, finer circuits
→ Becoming a general-purpose component
→ Structural shift into an industry where shortages can occur
- Key changes
1. Larger area: package area 30 → 100~150 body
2. Higher layer count: attempts to break through the limit from 30 layers → 50 layers
3. Finer circuits: Advanced SAP and BVH processes essential
→ A structure where capacity shrinks and unit prices rise
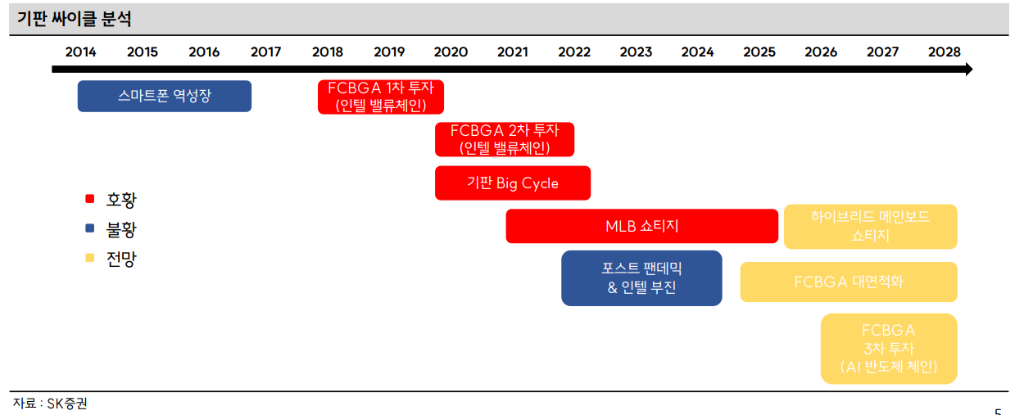
Cycle summary
- 2025
• Memory substrates rebound
• MLB shortage continues
• BVH process already in shortage
- 2026
• Full-fledged FCBGA rebound
• Explosive demand for large-area substrates for AI accelerators
• Price increases on the same products become a real possibility
- 2027 and beyond
• Second FCBGA big cycle
• Emergence of 150-body-class packages
• Supply and demand stay tight even with capacity expansion
“The essence of shortage”
What matters is not demand but process difficulty + yield
With large-area substrates
• Production volume falls
• Defect rates rise
• Yields plunge
→ Even for the same DPU
Yield of 95% when producing 100 units
Yield of 80% when producing 25 units
So
• Only companies with technological capability survive
• Only companies that can pass on prices remain
What is a shortage?
A state where demand is high but supply cannot keep up.
= A situation where goods are in short supply.
Materials are the real bottleneck
- The most severe shortages right now
• T-Glass (high-grade glass fiber)
• Gold plating (PGC) – gold prices soaring
• Ultra-thin copper foil for packaging substrates
- Points
• Not every substrate uses glass fiber
• It is needed intensively for NVIDIA AI substrates
• Oligopoly of Japanese companies → continued price increases
- Conclusion
Materials shortage = stronger bargaining power for substrate makers
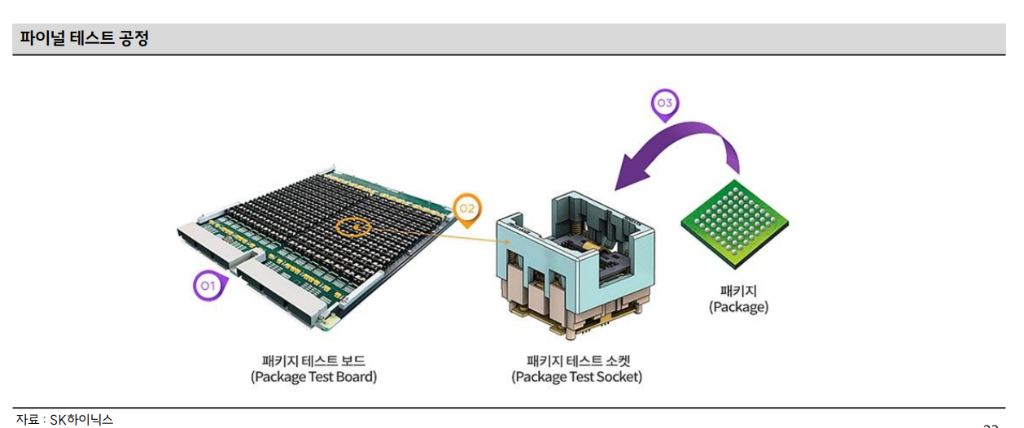
Test sockets go along for the ride
- Changes in AI GPUs
• Explosion in pin count (20,000~25,000 pins)
• Frequencies of tens of GHz
• TDP up to 1,000W
- So
• Increasing adoption of silicone rubber sockets
• Must handle high frequency + heat resistance + large area
→ Socket makers also see structural growth
Investment strategy portfolio suggested by securities firms
- Top picks
• ISU Petasys
• Samsung Electro-Mechanics
• Korea Circuit
- Second picks
• TLB
• Daeduck Electronics
• Lotte Energy Materials
- Watchlist
• Doosan
• LG Innotek
• Haesung DS
• Simmtech
• ISC
Summary
“Substrates are no longer a cyclical industry but
the bottleneck infrastructure of the AI era”
• More important than demand growth
→ is who is in shortage
• More important than revenue growth
→ is the possibility of price increases on the same products
So
2026 is
a period when earnings + valuations move at the same time